All Categories
Featured


Key Steps for Financial Freedom in 2026
Table of Contents
Throughout this time, the Department of Education might renew your responsibility to your loans if it's determined that you're no longer disabled, your family earnings surpasses certain permitted limits, or you get brand-new federal student loans. The Public Service Loan Forgiveness (PSLF) Program offers forgiveness for certain federal debtors who work for eligible companies.
To receive federal student loan forgiveness, you need to: Make 120 certifying payments towards your loansBe used by a U.S. federal, state, local, or tribal federal government, or a nonprofit company Work full-time for that agency or organizationOwe qualified Direct Loans (or combine other federal loans into a Direct Loan) Enlist in an income-driven payment planIf you avoid payments throughout your loan grace duration, while you're registered in school, or during particular deferment and forbearance durations, those won't count toward the 120 qualifying payments you require for loan forgiveness.

To get this advantage, you'll require to submit a PSLF type accrediting that you were used with a qualified organization or company throughout of the forbearance period. If you worked complete time for AmeriCorps or as a Peace Corps volunteer, you can count that time toward your certifying service requirement.
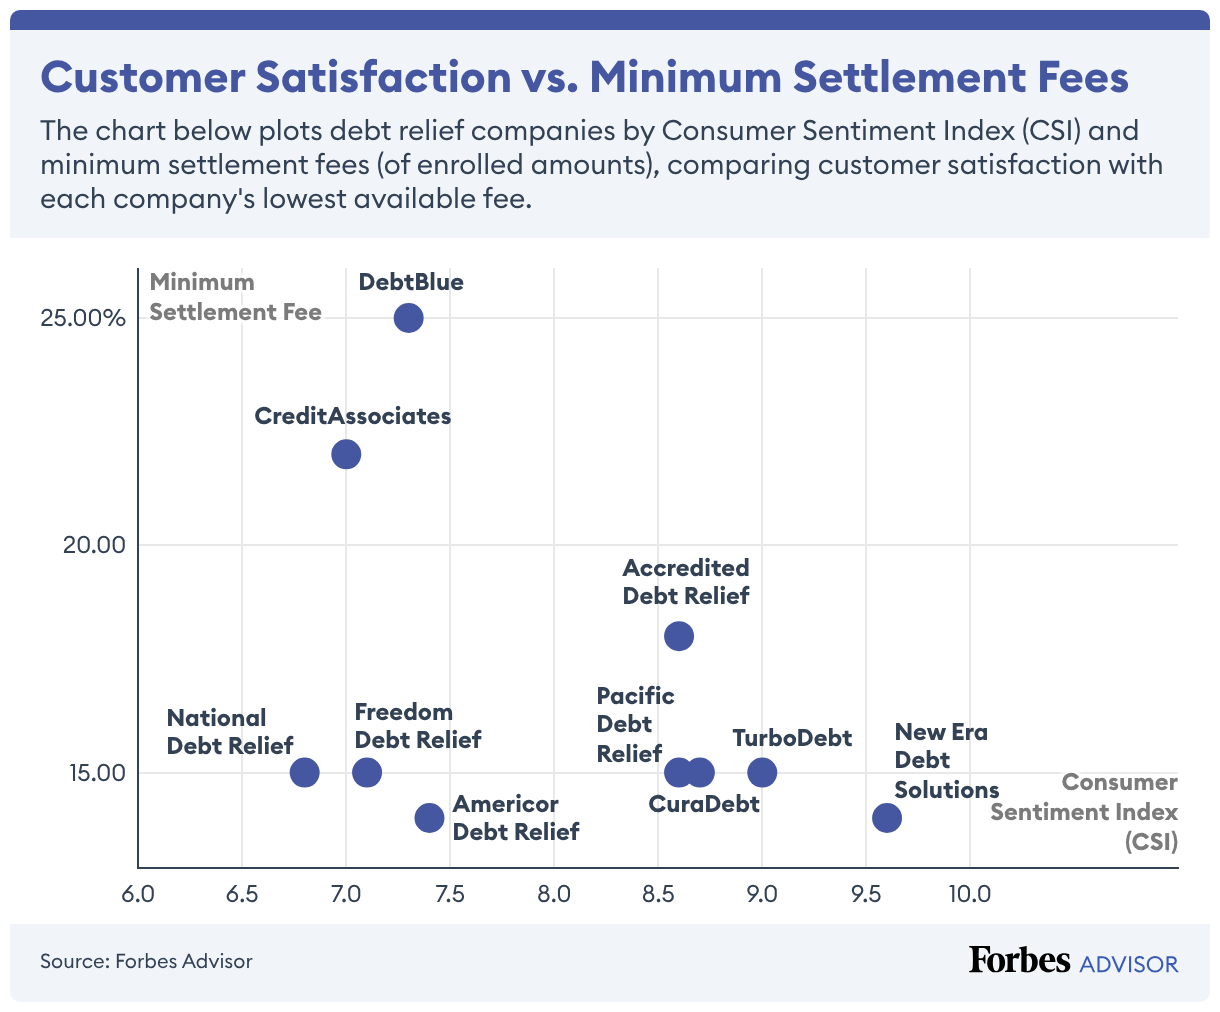
There is no government financial obligation relief program for credit cards. Financial obligation relief companies provide services to assist you manage and pay off credit card financial obligation for less than you owe. When you settle credit card financial obligation, you and the credit card business agree on an amount you'll pay, which is less than the overall balance you owe.
If you do not have a lump amount to offer your creditors (the majority of people don't), you might select to stop making credit card payments and rather set aside money in a devoted account. If you stop paying your creditors for any reason, expect credit score damage and collection efforts. When you have actually enough saved to use your creditors, negotiations can start.
Should You Consolidate High-Interest Debt in 2026?
Bankruptcy filings are public records and can make it hard to get tasks in certain fields. You also offer up control when you file bankruptcythe court informs you how much you will pay (Chapter 13) or what possessions you should quit (Chapter 7) to please your financial institutions. Personal bankruptcy has a significant unfavorable impact on your credit rating.
On the professional side, debt settlement might assist you get out of debt quicker than making minimum payments, given that you're paying less than the overall balance. A drawback of picking debt settlement for debt relief is that it's most likely to harm your credit standing. Keep in mind, nevertheless, that if you're already falling behind on your payments, the odds are excellent you have actually currently seen an unfavorable effect on your credit rating.
If you're thinking about charge card financial obligation relief programs, research your alternatives carefully. Check the services offered, the fees, and online reviews to see what other individuals are stating. Regardless of which financial obligation relief program you select, the most important thing is acting to get your finances and credit back on track.
Debtors with government trainee loans may certify for income-driven repayment plans. These plans can make a big distinction. This helps make sure you can pay for those payments.
Finding Financial Hardship Help in 2026
Working long enough in particular public service professions could certify you to have the rest of your debt forgiven. So could paying into an income-driven payment program for 20 or 25 years. If you've ended up being absolutely and completely disabled, you may not have to repay your trainee loans. Look for more information and to learn if you qualify.
For example, student loan special needs discharge needs proof of your condition. These programs are for individuals in genuine need, so not everybody will certify. In some cases, forgiven financial obligation is gross income. Debt forgiven under federal trainee loan programs is generally an exception. There are a few states where forgiven federal trainee loan debt might be dealt with as gross income.
Let's attend to some typical misconceptions about federal government debt relief programs to clean up any confusion. Reality: In numerous cases, IRS and trainee loan financial obligation forgiveness programs are based upon your capability to pay. While they minimize the amount you owe, they may not entirely eliminate your debt. Truth: Various programs have various eligibility criteria.
Federal government debt relief programs do not cover all types of financial obligation, but there are other choices that can assist. Here's what you can do if you have debt problems the federal government can't resolve.
Navigating the 2026 Debt Assistance Solutions
These organizations consist of personal financial obligation relief companies and not-for-profit credit counselors. Here are a few of the options they might use: Difficulty programs: Many creditors provide difficulty programs to assist you get through bumpy rides. These programs may decrease or pause payments, lower rate of interest, or waive fees for people experiencing monetary trouble.
Seeking 2026 Financial Hardship ReliefThis might lead to significant financial obligation reduction. Credit therapy: A licensed credit counselor can help you develop a budget plan and learn money management skills if you enroll in their financial obligation management program. If you have financial obligation problems, start taking steps to fix them: Connect to financial institutions to inquire about challenge programsTalk with a debt relief expert or credit therapist for a totally free consultationConsider which solution best fits your situationAct quickly so you do not develop up more financial obligation or face collection actionsGovernment debt relief programs might become part of the solution for you.
Millions of Americans are having a hard time with charge card financial obligation, and in 2026, some may receive relief through credit card financial obligation forgiveness programs. These initiatives, used by major charge card issuers and financial organizations, are developed to help qualified customers lower or eliminate impressive balances under specific conditions. Eligibility for charge card financial obligation forgiveness usually depends upon a number of key elements:: Individuals experiencing considerable monetary difficulties, such as task loss, medical emergency situations, or unanticipated family costs, might qualify.
Lenders may provide a settlement where a portion of the financial obligation is forgiven in exchange for a lump-sum payment or a structured repayment plan.: Some programs require proactive engagement with the charge card company. Consumers may deal with a financial therapist or straight with the financial institution to work out a settlement quantity that is lower than the total balance owed.
2026 Guide to Successful Debt Relief
This often needs careful budgeting to guarantee the settlement can be met in full.-: Structured payment programs collaborated by credit counseling companies may include forgiveness clauses if the consumer successfully completes the intend on time.-: Some providers provide temporary decreases in interest rates, waived costs, or partial financial obligation forgiveness to account holders experiencing monetary difficulty.

Latest Posts
Steps to Lower Credit Card Debt

Professional Analysis of 2026 Debt Consolidation Trends
Top-Rated 2026 Credit Relief Solutions for Households